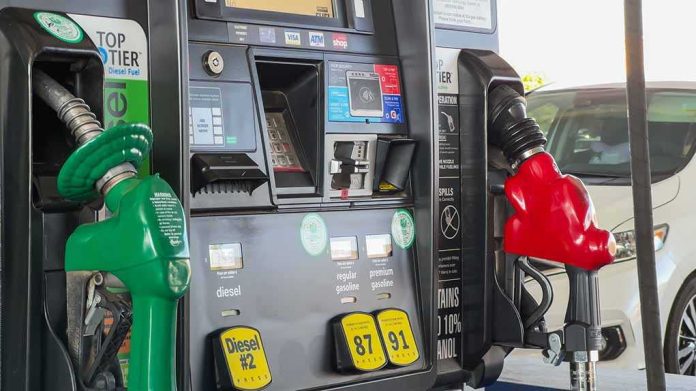
Tax policy can cut fuel bills overnight, but it does not manufacture a single new gallon of diesel; moves like opening access to tax-exempt red-dyed diesel change who pays the levy and when, not the underlying market price mechanics that drive most costs.
At a Glance
- President Trump signed an executive order that defers federal excise tax collection when dyed diesel is used on-road, widening access to tax-exempt “red-dyed” diesel in the near term.
- Red-dyed diesel is the same petroleum product as highway diesel, marked to designate tax-exempt, off-road use under IRS rules; historically, using it on-road has been illegal and penalized by states and the IRS.
- The executive action offers immediate cash-flow relief roughly equal to the deferred federal tax (24.4 cents per gallon), but analysts say it doesn’t change wholesale pricing or supply fundamentals, limiting pass-through to broader consumer prices.
- States warn that shifting dyed fuel into on-road use erodes road-fund revenues, which are largely financed by fuel excise taxes.
What the order does, and how dyed diesel works
The White House described the action plainly: it directs Treasury to defer payment of the federal excise tax when dyed diesel is used on-road for the remainder of the year, without interest or penalties. In U.S. practice, dyed diesel is ordinary diesel fuel marked with a red dye to signal exemption from the highway fuels tax when used for qualified off-road purposes—farm equipment, construction machinery, and certain heating applications—under Internal Revenue Code section 4082 and implementing regulations. The dye is an enforcement tool and a legal boundary, not a chemical change to performance. Historically, putting dyed diesel in a highway vehicle has been prohibited and policed through roadside inspections and stiff per-gallon penalties in many states; the dye makes violations easy to detect.
Because the underlying fuel is the same, the price wedge between dyed and undyed diesel has long reflected the tax burden and compliance costs. Recent empirical work from Colorado’s legislative analysts found distributors typically reduce the retail price of dyed diesel by roughly the sum of state and federal excise rates—evidence that the tax relief is largely passed through to end users in that off-road market segment. The federal component of that wedge is 24.4 cents per gallon for highway diesel, a figure that anchors what near-term savings can look like under federal relief scenarios.
What this changes in the real economy—and what it doesn’t
Tax deferral changes cash flow at the nozzle. For fleets, farms, and construction operators who can now legally buy dyed diesel for on-road use under the federal order, the immediate relief is bounded by the federal tax value itself: roughly a quarter per gallon. That is meaningful for high-volume diesel users with thin margins, because the savings compound across hundreds or thousands of gallons a week. But it does not alter crude benchmarks, refinery utilization, seasonal diesel demand, or the spot market spreads that set most of the retail price. Analysts who follow refined products markets therefore caution that expanding access to tax-exempt diesel will not lower the wholesale price refiners receive and will do little to correct supply tightness; the principal effect is lower (or delayed) tax collection rather than cheaper production. Those are base-rate constraints whenever policymakers reach for temporary fuel tax tools rather than supply-side levers.
Will consumers see cheaper groceries? In theory, lower input costs cascade through freight and production. In practice, the pass-through from a ~24-cent diesel tax deferral to store shelves is attenuated by how small fuel is as a share of delivered retail price, the heterogeneity of logistics contracts, and timing lags. As one agricultural economist put it, the administration’s version can help targeted users but “would not change the underlying wholesale diesel price,” which is what ultimately governs the broader pump price and most downstream freight contracts.
The legal and fiscal frame states operate in
For decades, the red dye has been the linchpin of a joint federal–state compliance regime. States emphasize the reason: without a visible marker, the incentive to evade fuel excise taxes is high, and losses mount quickly. Minnesota estimates that illegal dyed-diesel highway use costs several hundred million dollars per year in combined state and federal revenue, directly reducing funds available for roads and bridges. North Carolina underscores the same link—untaxed highway fuel use reduces revenues for highway construction and maintenance and carries criminal penalties for violators. Many states layer civil penalties on top; for example, Washington assesses the greater of $10 per gallon or $1,000 per tank for illegal dyed-diesel highway use.
Those enforcement structures were designed for a clear binary—dyed equals off-road. A federal order that defers federal tax on dyed diesel used on-road softens that binary on the federal side for a specified period. But the fiscal consequence that states worry about remains: excise taxes are user-fee proxies funding pavement, bridges, and safety infrastructure. If dyed fuel migrates into highway use broadly, state and federal road funds will collect less unless offset elsewhere. That is policy design, not a compliance accident.
How we got here: the recurrent politics of fuel tax relief
When diesel prices spike, executives and legislatures often reach for temporary tax relief because it is administratively fast and visible to constituents. The pattern is well documented in state actions during past price run-ups and in federal explorations of dyed-diesel flexibility: it can deliver immediate, measurable per-gallon savings to eligible users but does not expand refinery output or ease global supply constraints. In that context, the current order is a textbook application: it widens legal access to the already tax-free product and defers the federal levy when used on-road, advertising quick relief for high-mileage operators without repositioning supply chains.
Because dyed diesel is chemically the same as highway diesel, the savings are arithmetic—anchored to the foregone tax—and potentially substantial for specific operators with heavy diesel burn. But because the core price drivers remain crude, refining, and distribution, macro-level diesel prices and headline inflation are unlikely to budge on the strength of a tax deferral alone. That bifurcation—real relief at the margin, limited systemic impact—is why analysts typically describe such steps as palliative rather than curative.
What to watch next: distribution, compliance, and durability
Three practical questions will determine how much relief materializes at the nozzle. First, distributor behavior: when policy resets the tax line, do wholesale and retail prices for dyed product adjust one-for-one, as Colorado’s evidence suggests in off-road markets, or do frictions and inventory timing dilute pass-through under broader access? Second, compliance harmonization: federal deferral does not automatically change state law; uneven state responses could leave a patchwork of permissible on-road dyed-diesel use, complicating operations for interstate fleets and retailers. Third, sunset and settlement: a deferral moves the tax liability in time and may require later reconciliation unless the order is paired with subsequent action that eliminates the obligation altogether—a pathway the fact sheet signals Treasury will examine. Each of these factors will shape whether the measure delivers a short, sharp rebate for diesel-intensive sectors or a thinner, more idiosyncratic benefit.
The strategic trade-off is clear. If the goal is immediate cost relief for specific users during a price surge, expanding access to dyed diesel can work on contact. If the goal is lower economy-wide prices, the lever is blunt. Any durable reduction in diesel costs for households and businesses runs through supply—refining capacity, distillate yields, logistics—and demand adaptation, not dye.
President Trump signed an executive order aimed at bringing down near-record diesel prices by waiving restrictions on cheaper red-dyed diesel. https://t.co/pTqN63d1hs pic.twitter.com/3KIU4ZHd6X
— CNN Politics (@CNNPolitics) October 6, 2026
Bottom line
The executive order changes the tax line, not the physics or logistics of diesel supply. Expect tangible per-gallon savings for high-use operators while the order is in effect, bounded by the federal tax rate and any state actions. Do not expect wholesale prices—or the structure of road funding—to change in your favor without further policy work.
Sources:
youtube.com, news.bloomberglaw.com, thehill.com, irs.gov, politico.com, nebraska.tv, reuters.com, revenue.state.mn.us, ncdor.gov, investinglive.com