The striking shift in U.S. housing policy is not a talking point but a binding prohibition: Congress has made it illegal for large for‑profit landlords to keep accumulating single‑family homes, and Treasury’s proposed rule converts that statute into a transaction-by-transaction compliance regime with penalties calibrated to matter.
The Short Version
- Federal law now bars for‑profit entities that control at least 350 single‑family homes from buying additional one‑ or two‑unit houses, with time‑limited effect through 2042.
- Treasury’s proposed rule starts January 7, 2027 and defines how firms demonstrate eligibility, exceptions, and safe harbors before they bid.
- Violations can trigger civil penalties up to the greater of $1 million or three times the purchase price—plus litigation risk.
- The rule preserves build‑to‑rent and renovate‑to‑rent pathways under defined conditions, reflecting a surgical—not blanket—approach.
What the law actually does—and why the rule matters
Section 1001 of the 21st Century ROAD to Housing Act prohibits for‑profit entities with investment control of at least 350 single‑family homes from acquiring additional one‑ or two‑unit properties. In plain terms, once a landlord is large by statute, the growth-by-acquisition model in the existing single‑family stock is cut off nationwide. Enforcement is not symbolic: Treasury or the Department of Justice may seek a civil penalty up to the greater of $1 million or three times the purchase price for a prohibited deal, an amount designed to erase the upside from noncompliance and then some. The statute channels penalty revenue to homeownership activities under the HOME program, tying enforcement to a compensatory policy lever. The prohibition takes effect January 7, 2027 and sunsets after 15 years, in 2042—long enough to shape behavior, short enough to be credibly re‑evaluated.
The statute needed a mechanism to work in the real market, where offers are made under tight deadlines and through layered ownership structures. Treasury’s proposed rule supplies that mechanism. It sets an operational bright line: beginning January 7, 2027, any covered investor generally may not purchase—or even contract to purchase—a single‑family home unless the transaction qualifies as an “excepted purchase.” That phrasing matters; binding the contract stage prevents end‑runs via escrow timing or assignment tricks that would otherwise let prohibited deals close before scrutiny.
The exception architecture: preserving supply‑building activity while halting accumulation
Policymakers did not opt for a categorical ban. Treasury’s framework delineates exceptions and safe harbors aimed at distinguishing accumulation of existing stock from activity that plausibly adds or upgrades supply. Among them: build‑to‑rent, renovate‑to‑rent, homeownership and homeownership‑support programs, foreclosure‑related and certain debt‑satisfaction acquisitions, along with structured safe harbors for substantial rehabilitation, meaningful renter supports, rights of first refusal, and 30‑day first‑look periods for buyers outside the covered class. The through‑line is clear: let large operators build and improve, not hoover up starter homes in already tight neighborhoods. The structure also anticipates how deals are actually papered—by clarifying what documentation and thresholds are sufficient to claim protection up front.
Critics sometimes caricature such exception lists as loopholes; in practice, they are the only scalable way to keep useful capital in the system while drawing a hard line against practices lawmakers want to deter. Still, two implementation questions remain: aggregation (how indirect or affiliated ownership is counted toward the 350‑home threshold) and exception scope (how many real‑world transactions will qualify). Treasury’s rulemaking docket is the venue to pin those down with examples, organizational‑chart tests, and safe‑harbor metrics investors can verify pre‑bid.
Enforcement teeth and the compliance reality
The most consequential line in the rule is the penalty formula. Tying the maximum to the greater of $1 million or triple the purchase price ensures that violations on lower‑priced homes are not treated as a cost of doing business, and that luxury acquisitions cannot slip through with trivial fines. This design, combined with authority for DOJ referrals, creates real leverage in settlement and deterrence—especially when layered onto the prospect of rescission or voided sales in private litigation that may follow a government action. Institutional counsel are reading the same lines; they will budget for monitoring, auditing, and documentation to prove exception eligibility.
With that leverage comes procedural complexity. Expect guidance on: what counts as “investment control,” how to treat joint ventures and separately managed accounts, how violations are tallied across series LLCs, and how to handle multi‑property portfolio closings. A fact‑intensive regime is manageable if Treasury publishes checklists, examples, and a predictable examination cadence; it becomes uneven only when interpretive access is the scarce commodity. Transparency—around staffing, audit protocols, and early enforcement outcomes—will be as important to credibility as the statute’s plain text.
What the policy can and cannot change in the housing market
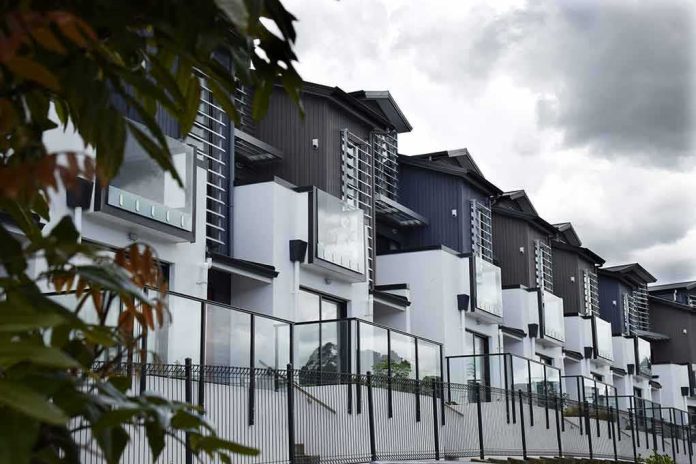
The legal question is settled; the market question is not. The rule will absolutely change who is permitted to bid on a universe of homes—especially in metros where large landlords are most active. Yet the national affordability needle is driven by interest rates, zoning, construction costs, labor, materials, and migration; nothing in the law lays new foundations or frames new homes. The best evidence we have says institutional owners remain a small share of the total single‑family stock nationally, though their presence can be material within the single‑family rental segment in selected Sun Belt metros. That concentration pattern—small in the aggregate, potent in submarkets—explains why some neighborhoods will notice the ban at the open house while others will not.
Industry and academic critics make three coherent points. First, by constraining future acquisitions that would otherwise become rentals, the rule could reduce the supply of single‑family rentals and nudge rents up for households who must rent—particularly in neighborhoods where renting a detached home is the path to a yard, a school catchment, or a shorter commute. Second, because large landlords account for only a few percentage points of total transactions nationally, disallowing their bids may not register in national price indices even if it shifts outcomes locally. Third, compliance costs and financing ripple effects could tighten liquidity in single‑family‑rental securitizations over time. Those are not straw men; they are foreseeable consequences that should be watched in the data.
How to judge success: evidence, not vibes
There are credible ways to test this policy’s real effects once it takes hold. The most informative approach will use property‑level comparisons, not just metro averages: track bids, bidder type, financing, inspection waivers, and closing prices for homes that would have attracted covered investors before January 2027 versus similar homes after. Pair that with renter outcomes: inventory and rents for single‑family rentals by school district and census tract. A difference‑in‑differences design—comparing high‑exposure tracts to matched low‑exposure tracts—can isolate policy effects from broader rate cycles or construction swings. Treasury and housing agencies already hold much of this data; publishing de‑identified extracts would allow independent replication and keep the debate empirical.
On enforcement credibility, early signals matter. How many pre‑contract inquiries arrive? How often do firms invoke exceptions, and what share pass muster? What penalties are assessed in the first year, and at what step do cases settle? Disclosing aggregate figures and anonymized case studies would show whether the $1 million‑or‑triple‑price stick is changing behavior or only generating paper. If the rule reliably prevents prohibited bids from reaching the contract stage in targeted submarkets—while permitting build‑to‑rent and substantial‑rehab pipelines to continue—then it will be working exactly as designed, regardless of whether national prices budge.
🏠Treasury Unveils New Rules for Big Investor Homebuyers After Congress Set Limits
The Department of the Treasury unveiled the proposed rule that establishes standards for large institutional investors in the housing market.
🧑⚖️ It follows a January executive order from… pic.twitter.com/4B1DMaicE5
— QSI Media – News, Analytics, World. (@MediaQSI) October 23, 2026
Bottom line for owners, renters, and investors
For owner‑occupant buyers competing in neighborhoods where large landlords were frequent winners, the playing field should tilt in your direction beginning in 2027; fewer deep‑pocketed, as‑is offers will show up. For renters who value single‑family homes, the effect is more ambiguous: reduced future acquisitions by large operators could slow additions to that rental stock, while renovation and build‑to‑rent exceptions keep some supply flowing. For covered investors and their lenders, the era of growth by acquisition in the existing single‑family market is over, at least for this policy’s 15‑year run. The smart strategy now is compliance by design—clear ownership aggregation, pre‑bid exception vetting, and documentation robust enough to withstand the rare but consequential day when a $1 million question shows up in the mail.
Sources:
congress.gov, lw.com, federalregister.gov, brookings.edu, cnn.com, cnbc.com, housingwire.com, wellington.com